In short
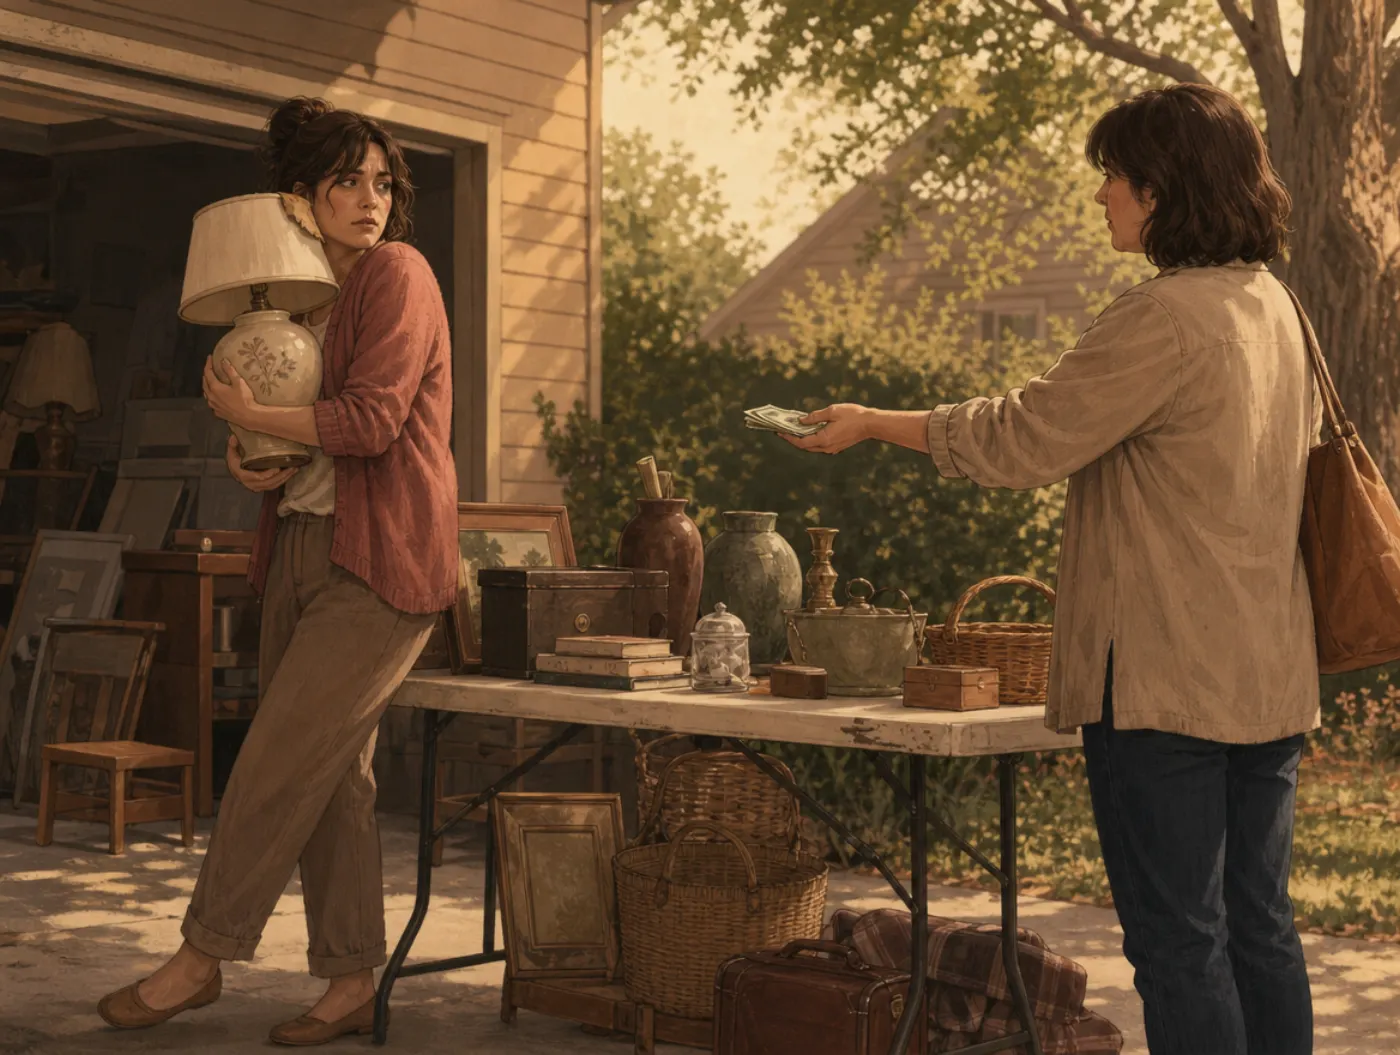
The endowment effect is the tendency to value a thing more highly once you own it, so that the price at which you would sell it is well above the price you would have paid to buy it. It shows up in used-car and house negotiations, in free trials that are hard to cancel, in unsold inventory, and in the classic experiments where students given a coffee mug would not part with it for twice what other students would pay.
How the endowment effect works
Standard economics says the value of a mug does not depend on whose hands it is in. If a mug is worth four dollars to you, you should buy below four and sell above four, and in a room where mugs are handed out at random about half should change hands. They do not. Selling prices come in at roughly twice buying prices, and most mugs stay where they were put.
The first explanation came from prospect theory. Giving up something you own is coded as a loss, acquiring the same thing as a gain, and Kahneman and Tversky's 1979 value function makes losses weigh more heavily than equivalent gains. On that account the mug's price rises the moment it is yours.
That account has since been narrowed. Carey Morewedge and colleagues noted in 2009 that the standard experiment confounds owning with selling. In two experiments that pulled them apart, ownership produced the effect and selling did not: the gap disappeared when buyers owned a mug of their own and when sellers were brokers who owned nothing. On that reading the mug is overpriced because it is associated with the self, not because parting with it is expected to hurt.
The effect also has an exchange version with no prices at all. In a study Knetsch ran in 1989, three classes chose between a mug and a chocolate bar. In the class first given mugs, 89 percent kept the mug; in the class first given chocolate, 10 percent switched to the mug; in the class offered a free choice, 56 percent took the mug. The same two objects produced three answers depending on which was already in hand.
How much of the laboratory gap is the effect and how much is the method is a live dispute. Charles Plott and Kathryn Zeiler reported in 2005 that with extensive training on the pricing mechanism, an incentive-compatible procedure and anonymous responses, the gap between willingness to pay and willingness to accept disappeared, which they read as evidence of subject misconceptions. Isoni, Loomes and Sugden went back to the question in 2011. Their new experiments confirmed the missing gap for mugs, but the same procedures applied to lotteries produced a significant and persistent gap, in their own data and in data from the 2005 study that had not been published; Plott and Zeiler replied in the same issue. Morewedge and Giblin's 2015 review treats the effect as real with several mechanisms competing to explain it. The practical lesson holds either way: the price you would accept and the price you would pay are usually different numbers, and ownership is one of the things that can pull them apart.
The original study
Daniel Kahneman, Jack Knetsch and Richard Thaler published "Experimental tests of the endowment effect and the Coase theorem" in the Journal of Political Economy in 1990. Their design answered the standard objection to earlier work, that the gap between buying and selling prices reflects transaction costs or confusion rather than value.
Each session began with markets in induced-value tokens, where each participant was told in private what a token was worth to them in cash. Those markets worked about as theory predicts: median buying and selling prices were identical, and the number of trades came within one of the prediction in every round. The same people then traded Cornell coffee mugs, priced at 6 dollars in the campus store, under procedures that were otherwise identical. Median selling prices came in at more than twice median buying prices, and the volume of trade was a fifth of what was predicted.
The fifth experiment removed one more objection by making the price random, so that no one had a strategic reason to shade their answer. Mugs were given to 30 potential sellers while 29 potential buyers were shown one. Each person marked, for every price from 0 to 9.50 dollars, whether they would sell or keep, or buy or not buy; a price was then drawn at random and the trades at that price were carried out. The median selling price was 5.75 dollars and the median buying price 2.25, with means of 5.78 and 2.21. Random assignment should have produced about 14.5 exchanges. Six were indicated.
The authors drew two conclusions. The gap is not a transaction cost, since token markets run with the same procedures cleared normally, and it does not wash out with experience, since it persisted over four rounds with real money and real mugs.
Everyday examples
The effect appears wherever ownership is settled before a price is discussed. The rows below are illustrations, not study findings.
| Situation | What the bias does | What helps |
|---|---|---|
| Selling a used car or a house | The asking price reflects what the owner needs to give it up, above what buyers will pay | Price from recent completed sales of comparable items, not from what it would take to persuade you |
| A free trial that starts automatically | Thirty days of ownership makes canceling feel like losing something, which is what the trial is for | Decide on the day you sign up whether you would pay full price, and set a reminder |
| Clearing out a wardrobe or a garage | Each item is worth keeping, though you would not buy any of them again today | Ask of each one whether you would pay today's price for it today, and treat no as a sale |
| Holding a losing investment | The position is valued at what it would take to let it go rather than at what it is worth now | Write the sell conditions when you buy, and act on the written rule |
| Negotiating over something already allocated | Whoever holds the asset values it more, so the deal space is narrower than it looks | Agree the valuation method before the asset is assigned, and use an outside price where one exists |
How to counter it
The effect comes from where the thing sits rather than from a belief you could argue with, so the counters change the question.
- Ask the buyer's question about what you already own: if I did not have this, what would I pay for it today? A gap between that and your asking price is worth examining, since ownership is one of several things that can produce it.
- Use an outside number. Completed sale prices, a market quote or a published index do not depend on who is holding the item.
- Decide before you own it. A written sell price, a cancellation date or an exit condition set at the time of purchase is made by someone who has nothing to lose yet.
- Put the decision in someone else's hands for a moment. The 2009 experiments found no effect for brokers who owned nothing, which is why asking a friend what they would take for it helps.
- Expect free trials and free samples to work this way. Giving you the thing is the cheapest way to raise the price you will accept to give it back.
- In negotiations, set the valuation rule before assets are divided. Afterwards each side prices what it holds above what the other will pay.
What it is not
The endowment effect is about ownership raising a price. Its neighbors are about losses, inertia and effort.
- It is not loss aversion, the asymmetry between the weight of losses and equivalent gains. That was the first explanation offered here, and the 2009 ownership experiments suggest it is not the whole story.
- It is not status quo bias, the preference for leaving things as they are. The two usually push the same way, but status quo bias covers any default, including arrangements nobody owns.
- It is not the IKEA effect, where the value added comes from having built the thing yourself. Being handed a mug involves no labor at all, which is what makes the price gap surprising.
- It is not the sunk cost fallacy, where past spending justifies more spending. The mug cost its owner nothing.
Go deeper: the free Endowment Effect mini course
Twelve to fifteen minutes, in your browser, with the research behind the bias and the counter-measures that have evidence.
Tests and tools that use this
Related biases
Endowment Effect FAQ
What is the endowment effect?
It is the tendency to value something more once you own it, so that the lowest price at which you would sell it exceeds the highest price you would have paid for it. Kahneman, Knetsch and Thaler demonstrated it with coffee mugs in 1990: the median selling price was 5.75 dollars against a median buying price of 2.25, and most mugs stayed with whoever had been handed one.
What was the coffee mug experiment?
Students were given mugs at random and markets were run for them. In the fifth experiment, 30 people were given a mug and 29 were not, and each marked whether they would sell or buy at every price from 0 to 9.50 dollars, after which a price was drawn at random. Random assignment should have produced about 14.5 trades; the prices people marked implied six. Markets in tokens with known cash values, run with the same procedures, cleared about as predicted.
How does the demo on this page work?
When the page loads it assigns you one of the two versions using a value kept only in your browser's session storage, so a reload shows the same one. In one version the mug is yours and you name a selling price; in the other it belongs to your neighbor and you name a buying price. Both are hypothetical, where the 1990 experiments used real mugs and real money. Once each version has 50 responses the splits appear side by side.
What causes the endowment effect?
The original account was loss aversion: giving up the mug is coded as a loss, which weighs more than the equivalent gain. Morewedge and colleagues complicated that in 2009 by separating ownership from selling, and found that ownership produced the effect while the act of selling did not, pointing to an association between the object and the self. Morewedge and Giblin's 2015 review treats several mechanisms as live.
Is the endowment effect real or an artifact of the experiments?
This is argued over. Plott and Zeiler reported in 2005 that with extensive training on the pricing procedure, an incentive-compatible mechanism and anonymous responses, the gap between willingness to pay and willingness to accept vanished, which they read as evidence of subject misconceptions. Isoni, Loomes and Sugden confirmed the missing mug gap in 2011, but found a significant and persistent gap when the same procedures were applied to lotteries. The exchange asymmetry with real goods has been harder to explain away.
How do I avoid the endowment effect when selling something?
Price from outside your own position. Look up completed sales of comparable items, and ask what you would pay for the thing today if you did not already have it; any difference between that and your asking price is a prompt to check what ownership is doing to your number. Writing a sell price at the moment you buy, before ownership has done its work, is the version of this that takes no willpower later.
References
- Kahneman, D., Knetsch, J. L., & Thaler, R. H. (1990). Experimental tests of the endowment effect and the Coase theorem. Journal of Political Economy, 98(6), 1325-1348. doi.org
- Kahneman, D., & Tversky, A. (1979). Prospect theory: An analysis of decision under risk. Econometrica, 47(2), 263-291. doi.org
- Morewedge, C. K., Shu, L. L., Gilbert, D. T., & Wilson, T. D. (2009). Bad riddance or good rubbish? Ownership and not loss aversion causes the endowment effect. Journal of Experimental Social Psychology, 45(4), 947-951. doi.org
- Plott, C. R., & Zeiler, K. (2005). The willingness to pay-willingness to accept gap, the "endowment effect," subject misconceptions, and experimental procedures for eliciting valuations. American Economic Review, 95(3), 530-545. doi.org
- Isoni, A., Loomes, G., & Sugden, R. (2011). The willingness to pay-willingness to accept gap, the "endowment effect," subject misconceptions, and experimental procedures for eliciting valuations: Comment. American Economic Review, 101(2), 991-1011. doi.org
- Morewedge, C. K., & Giblin, C. E. (2015). Explanations of the endowment effect: An integrative review. Trends in Cognitive Sciences, 19(6), 339-348. doi.org
Cite this source
Psychology.com. (2026, October 21). Endowment Effect. Psychology.com. https://psychology.com/biases/endowment-effect